What’s the minimum deposit to buy a home in Karratha or Port Hedland?
The minimum deposit to buy a home in Karratha or Port Hedland is smaller than most people think. Some lenders offer loans with around a 10 per cent deposit and no lenders mortgage insurance in WA's larger regional centres, and not just for first home buyers. Here is how that door opens, as at September 2026.
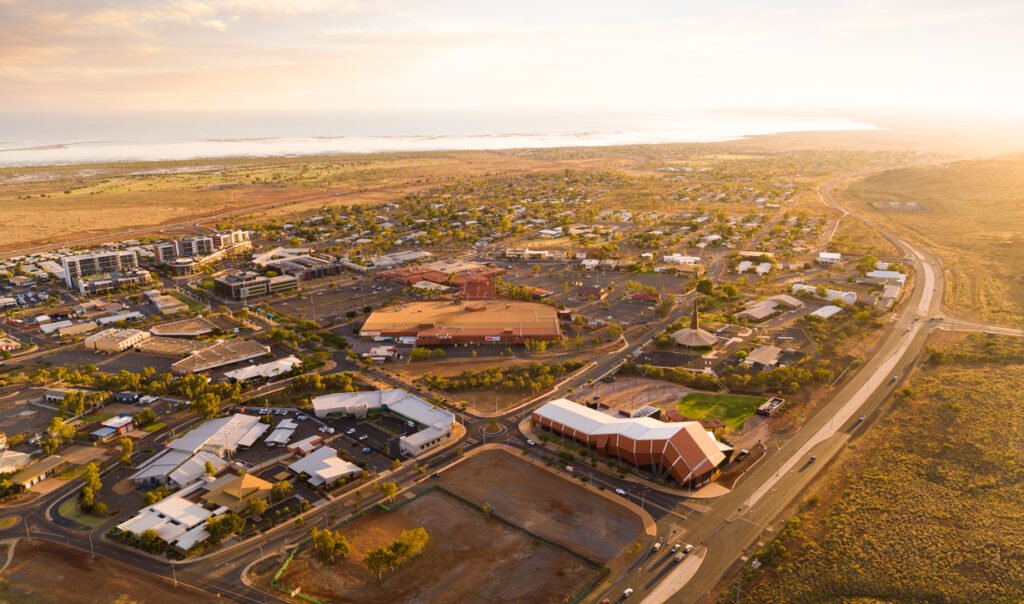
Short answer: the minimum deposit to buy a home in Karratha or Port Hedland can be around 10 per cent with some lenders, with no lenders mortgage insurance on top. And here is the part almost nobody up north has heard. You do not have to be a first home buyer to get it. Everyone assumes a low deposit with no LMI means a government scheme with a first home rule attached. In Karratha, Port Hedland and South Hedland, that assumption is out of date. And it is not just a Pilbara story: the same door opens across WA’s larger regional centres, from Kalgoorlie to Geraldton to Bunbury. The full 20 per cent deposit most people are quietly saving towards is a habit, not a rule. Here is what is on offer, who it covers, and what the numbers look like town by town, as at 16 September 2026.
What’s the minimum deposit to buy a home in Karratha or Port Hedland?
Short answer: with some lenders on our panel, around 10 per cent of the purchase price for an owner-occupied purchase. No lenders mortgage insurance is charged, and repayments are principal and interest. That is the working minimum deposit in these towns right now for standard employment income, as at September 2026.
The 20 per cent benchmark exists for one reason. Lenders mortgage insurance is usually charged once a loan goes above 80 per cent of the property’s value, and it protects the lender, not you. So most buyers either save the full 20 per cent or wear a premium that can run to five figures. What has changed: some lenders now lend up to 90 per cent in larger regional centres without charging LMI at all. Not a waived premium hidden in the rate. Not an insurance bill added to the loan. The deposit hurdle halves and the insurance line item disappears. With more than 60 lenders on our panel, policies like this vary widely. That is exactly why the minimum deposit is a conversation, not a single number.
Do you have to be a first home buyer to get a low deposit with no LMI?
Short answer: no. This is lender policy, not a government scheme, so there is no first home test. Upgraders, second-time buyers and people who already own elsewhere can all use it for an owner-occupied purchase in these towns, subject to normal lending assessment.
This is the bit worth reading twice. The Australian Government 5% Deposit Scheme is a genuinely good pathway. Since 1 October 2025 it has carried no income caps and no LMI. But it is built for first home buyers with a 5 per cent deposit, and for single parents or legal guardians with 2 per cent. If you have owned before, that door is closed to you. What we are describing here is different. It is ordinary lender credit policy that treats a 10 per cent deposit in a larger regional centre as an acceptable file without insurance. Some lenders even extend the same setting to investment purchases on principal and interest repayments. No first home scheme has ever done that. Weighing a home in town against an investment while you live on site? Our guide on buying in Perth while working in the Pilbara walks that fork in the road.
Why do people think mining towns need bigger deposits?
Short answer: because for years the story was postcode caution, with some lenders applying lower maximum lending in resource towns. That caution still exists at parts of the market. But it is not the whole market: larger centres with established populations are treated as standard security by a number of lenders.
Karratha and Port Hedland sit in single-industry country, and lenders have long memories of past cycles. So the folklore says you need a bigger deposit up here, not a smaller one. The reality in 2026 is more nuanced, and more positive. Policies that open the 10 per cent door commonly turn on the size and depth of the town, not its industry. Population thresholds around the 10,000 mark appear in some lenders’ settings.
Which WA centres clear the bar?
We write loans across every corner of this state, so here is the expert sweep, using ABS 2021 census figures for each urban centre. In the Pilbara: Karratha, at around 17,000 people, and the Port Hedland and South Hedland centres, at around 15,300 together, both clear a 10,000 threshold comfortably. In the Goldfields, Kalgoorlie-Boulder sits near 29,000. In the Mid West, Geraldton is around 38,600. Down south, Bunbury at 76,000-plus, Busselton around 40,500 and Albany around 35,000 are the giants of regional WA. In the Kimberley, Broome is around 14,700, and on the south coast Esperance clears 10,000 by a whisker. Smaller towns such as Newman, Tom Price, Onslow and Carnarvon sit under that mark and are assessed differently lender by lender. If that is where you are buying, talk to us and we will place the file where it fits.
How does a 10 per cent minimum deposit change the maths in these towns?
Short answer: it roughly halves the savings hurdle. On Port Hedland’s median house of $590,000, a 20 per cent deposit is $118,000 and 10 per cent is $59,000. On Karratha’s median of $720,000, it is $144,000 against $72,000. Years of saving, returned to you.
Numbers beat folklore, so here is the whole board. Every median below comes from REIWA’s March 2026 quarter regional data, and every deposit figure is simple arithmetic on it, rounded and for illustration only.
Now put those numbers against local rents. The same REIWA data has Karratha’s median weekly rent at $1,450, up 31.8 per cent over the year and the most expensive regional rental market in the state. Saving an extra $72,000 while paying rent like that is the treadmill many local households are on. A realistic minimum deposit changes the timeline from someday to this year. These figures are illustrations of the maths, not a quote or an assessment. Your own numbers depend on the property, the lender and your circumstances.
The deposit gap, centre by centre
WA regional centre medians and the 20 vs 10 per cent deposit gap (REIWA, March 2026 quarter)
| Centre | Median house sale price | Deposit at 20 per cent | Deposit at around 10 per cent |
|---|---|---|---|
| Karratha | Median $720,000, up 18 per cent over the year. | $144,000 before buying costs. | About $72,000, with no LMI at some lenders. |
| Port Hedland | Median $590,000, up 6.9 per cent over the quarter. | $118,000 before buying costs. | About $59,000, with no LMI at some lenders. |
| Kalgoorlie-Boulder | Median $440,000, up 10.3 per cent over the year. | $88,000 before buying costs. | About $44,000, with no LMI at some lenders. |
| Geraldton | Median $600,000, up 21.2 per cent over the year. | $120,000 before buying costs. | About $60,000, with no LMI at some lenders. |
| Bunbury | Median $710,000, up 14.5 per cent over the year. | $142,000 before buying costs. | About $71,000, with no LMI at some lenders. |
| Busselton | Median $1,020,000, up 14.3 per cent over the year. | $204,000 before buying costs. | About $102,000, with no LMI at some lenders. |
| Albany | Median $750,000, up 24.4 per cent over the year. | $150,000 before buying costs. | About $75,000, with no LMI at some lenders. |
| Broome | Median $790,000, up 6.6 per cent over the year. | $158,000 before buying costs. | About $79,000, with no LMI at some lenders. |
| Esperance | Median $585,000, up 17.6 per cent over the year. | $117,000 before buying costs. | About $58,500, with no LMI at some lenders. |
The 20 per cent deposit is a habit, not a rule. In WA’s big regional centres, the door opens at 10.
What conditions come with a 10 per cent deposit and no LMI?
Short answer: the settings that matter most are principal and interest repayments, standard employment income, and a purchase in an eligible larger town. Interest-only lending commonly still needs around a 20 per cent deposit, and refinances carry their own equity levels. Every lender draws these lines a little differently.
A few settings to know, all as at 16 September 2026. All of them move, which is why we check policy on the day we place a file. These loans commonly run on principal and interest repayments. Interest-only structures generally sit at lower maximum lending, around 80 per cent. Refinances are welcome too: owner-occupied commonly around 15 per cent equity, investment around 20. Very large applications at the highest lending levels can carry size caps. On the income side, permanent, casual and contract employees are commonly all accepted. If you are self-employed, this particular door is drawn for employees. That is a placement question, not a dead end. Our self-employed lending options cover low deposit paths of their own, so have a chat and we will find the lane that fits.
From the broker’s desk: this is our home turf. We are headquartered in Karratha and write loans from Hedland to Albany every week, and the deposit conversation in regional WA has been stuck on 20 per cent while lender policy quietly moved. The files we love are the ones where someone walks in convinced they are two years of saving away, and walks out with a plan for this year. Bring us your payslips and your number, and we will tell you honestly where you stand across the panel. Every situation is different, and there is usually more than one way to approach it.
How do you get started from here?
Short answer: work out your buying number, line up your deposit and payslips, and have the policy checked against your actual situation before you start inspecting. A pre-approval built on the right lender’s settings lets you offer with confidence on your minimum deposit, not someone else’s rule of thumb.
- Price your target honestly. Know the streets and the price bracket you are actually shopping in, not just the town median.
- Count everything in your deposit. Savings, equity, a gift from family. The path to 10 per cent is often closer than the path to 20 looked.
- Get the income evidence together. Recent payslips and your employment contract do most of the work for permanent, casual and contract roles.
- Have the policy matched to you. With 60+ lenders on the panel, the job is finding whose settings fit your town, your property and your income on the day.
- Go shopping pre-approved. In markets moving like these, the ready buyer wins the keys.
Lender credit criteria and scheme settings change. Everything above is general information current at 16 September 2026, not an assessment of your situation. What does not change is the shape of the opportunity. From Karratha to Kalgoorlie to the South West, the minimum deposit is smaller than the folklore says, and the first home rule does not apply to it. Finding out where you stand costs you a phone call. Message us and we will take a proper look.
About Pilbara Finance
WA-owned, servicing Western Australia and clients Australia-wide.
We compare the options across the panel and give a solid recommendation based on your circumstances.
Sound like your situation?
Twenty minutes on the phone, no paperwork to start. We will tell you what your income looks like to a lender before you go anywhere near one.
Start with a chatThis guide is general information for the Australian market, not advice about your situation. Lender credit policy changes, and what applies to you depends on your circumstances. Pilbara Finance is a credit representative (478535) of Mortgage Specialists Pty Ltd, Australian Credit Licence 387025.